


New Law – Pension System
On March 26, 2025, Law No. 21,735, which establishes a new Mixed Pension System, was published in the Official Gazette, introducing significant changes to Chile’s pension system.
The new legislation transforms the current individual capitalization system into a mixed system through the creation of a Social Security Pension Fund. This fund will be financed through permanent and transitional employer contributions, which will be paid into the Autonomous Pension Protection Fund, administered by the same social security system.
In this context, the law establishes the gradual implementation of an additional employer contribution equivalent to 8.5% of each employee’s pensionable remuneration, distributed as follows:
- 1. Gradual allocation of 6.0% of the employee’s pensionable remuneration to their capitalization accounts, as follows
- 4.5% will be allocated to the employee’s individual capitalization account.
- 1.5% will be allocated to a protected-return contribution intended to help finance the benefit for years of contributions through the Autonomous Pension Protection Fund.
- 2. The remaining 2.5% of the Social Security Pension Fund contribution will be allocated to the Autonomous Pension Protection Fund, as follows:
- 1.5% currently paid by the employer for Disability and Survivorship Insurance (SIS).
- 1% for the new compensation for women, reflecting their longer life expectancy compared to men.
This contribution will be implemented gradually, according to the following schedule:
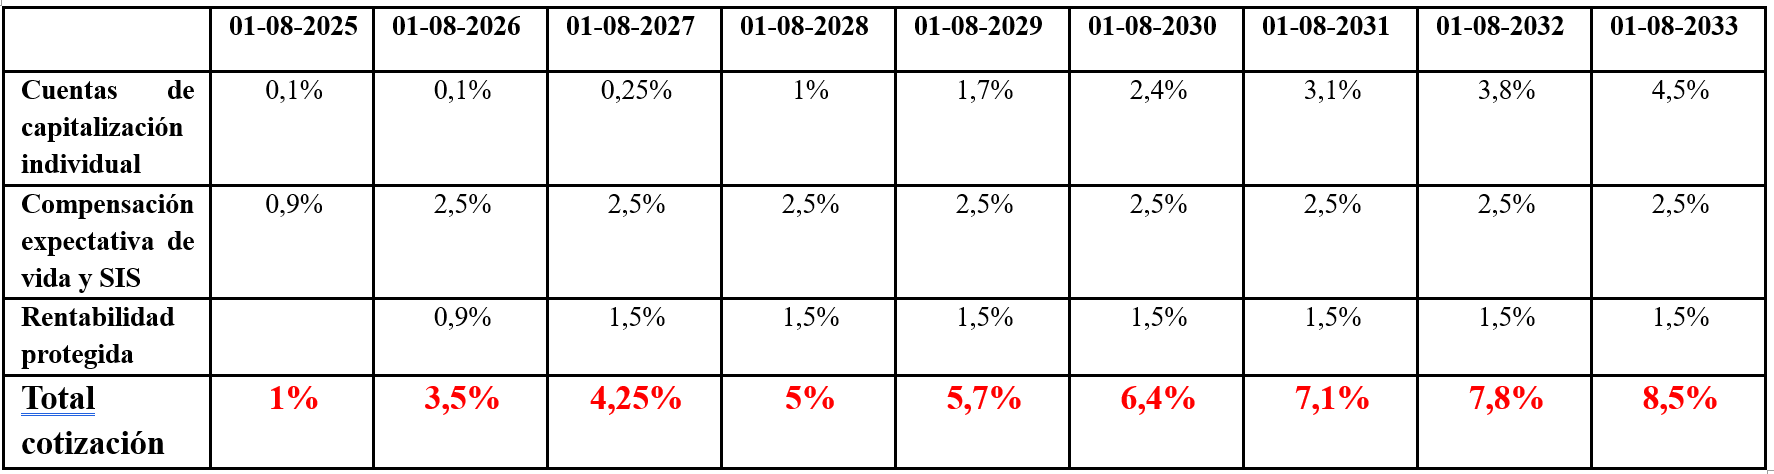
The actual increase in contributions under this new law will be 7%, since employers already contribute 1.5% for Disability and Survivorship Insurance (SIS).
Accordingly, as of August 1, 2025, the obligation to pay an additional 1% contribution will take effect, borne exclusively by the employer.
This 1% contribution is broken down as follows:
- 0.1% will be allocated to the employee’s individual capitalization account; and
- 0.9% will be allocated to a Social Security Pension Fund to finance the life expectancy compensation for female employees and the future bonus for years of contributions.
The maximum monthly pensionable remuneration will remain subject to the limit established in Article 16 of Decree Law No. 3,500 of 1980.
Finally, for income tax purposes, this additional contribution will be considered a pension benefit for the employee. For expense deduction purposes, it will fall under Article 31, paragraph 4, No. 6 of the same law, meaning it will be treated as “salaries, wages, and other remuneration.”
For further information, please contact Gonzalo Aravena at garavena@lembeye.cl